Physician Assistant Professional Liability Insurance
Physician assistant professional liability insurance protects PAs financially and professionally when a patient alleges negligence, error, or omission in the course of care. Providing medical malpractice coverage since 1947, CM&F Group has protected healthcare professionals from malpractice claims longer than any provider in the market. Coverage includes all PA specialties, from surgical and cosmetic to emergency medicine, orthopedics, and family practice.
- Endorsed by the AAPA for 25+ years, with a 10% premium discount for members who complete risk management courses
- A++ Superior rating from AM Best, the highest financial strength rating possible
- Insuring PAs since the inception of the profession, and providing medical malpractice coverage since 1947
- Coverage for all PA specialties, including surgical and cosmetic
- Average savings of 20% or more compared to competitors
- New graduate credit starting at 80% in your first year of practice

Every PA. Every Specialty. Every Career Stage.
CM&F has covered PAs across every specialty and practice setting, individual PAs and group practices, new graduates and seasoned clinicians. Coverage applies to services within your Scope of Practice (SOP) authority as defined by your state of practice and your practice agreement. There’s a policy built for where you are and where you’re headed.
Coverage for Individuals
Coverage for Groups









Nurse Practitioner Malpractice Insurance — What It Costs
Year 1 rate only. Premium increases annually until it doubles or triples. Tail coverage* is an additional cost at separation.
Stable annual rate, no maturation schedule, no tail coverage* required at separation. Any incident during your policy period is permanently covered, regardless of when a claim is filed.
Why CM&F Makes Occurrence-Based Coverage Our Standard
Many insurers advertise their lowest first-year claims-made rate as the headline price, then raise that rate every year until it doubles or triples. When you leave or retire, you pay separately for tail coverage to stay protected for past work, at 150% to 200% of your final annual premium for as much as 5 to 7 years.
CM&F made occurrence-based coverage our standard because over a PA’s career it is almost always the less expensive choice, and always the more certain one. Any incident during your policy period stays covered, no matter when the claim is filed.
*Tail coverage protects against claims filed after policy termination within your state’s statute of limitations, generally 5 to 7 years, and typically costs 150% to 200% of your final annual premium. P1, P2, and P3 are the specialty risk tiers used on your PA application. Starting rates reflect the lowest filed premium for each tier and vary by state, territory, coverage limits, and individual practice. Claims-made and occurrence rates are filed at different limits, as shown on each card. Source: MedPro Group filed state rate pages, distributed through CM&F Group. Final premium is confirmed at application.
How Your State Shapes PA Practice
A physician assistant’s practice environment depends on the state. The American Academy of Physician Associates classifies every state as Optimal, Advanced, Moderate, or Reduced based on its PA practice laws and regulations. Your state’s category affects how your scope of practice is defined and what relationship with a physician your state requires.
CM&F covers PAs in all 50 states across every practice category. Find out how your state classifies PA practice, and what it means for your coverage.
Learn More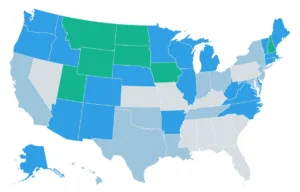
Policy Details
CM&F physician assistant professional liability policies cover legal defense, regulatory actions, and patient injury claims. Coverage includes full consent to settle, 24/7 portable protection, telehealth services, license defense, and Good Samaritan acts. A defense attorney is provided at no impact to your coverage limits. Key policy details are below.
Policy Coverage Limits
You have the final say when it comes to settling a suit. We will not settle without your consent, and you have the right to take a claim to court.
Up to $6 million aggregate for all covered claims within the policy period.24/7 Portable Coverage
Your policy covers you anytime, anywhere you provide services outlined within your scope of practice according to relevant state laws, as outlined within your policy agreement. This includes full-time, part-time, telehealth, locum tenens, PRN, per diem or moonlighting assignments, and volunteer work.
Full Consent to Settle
You have the final say when it comes to settling a suit. We will not settle without your consent, and you have the right to take a claim to court.
Telemedicine / Telehealth Coverage
Good Samaritan Acts Coverage
Good Samaritan Acts coverage protects you up to the limits of your policy if anything goes wrong while providing emergency care to a non-patient.
Assault Upon You
Your policy will include coverage for expenses occurring from a bodily injury or damage to your personal property resulting from an assault while traveling to and from your place of employment.
First Aid Expenses
CM&F professional liability policies cover up to $25,000 for expenses incurred while rendering first aid to another individual.
Medical Payments
Your CM&F policy includes coverage up to $25,000 per claim / $100,000 aggregate for medical expenses incurred by others as a result of a covered incident.
Deposition Fees Coverage
Even if you are not named in a lawsuit, there may be scenarios where you are required to attend a deposition. Your policy covers up to $25,000 in reasonable fees, costs and expenses necessary to represent you at a deposition.
License Defense/Administrative Hearing Expense Coverage
Your policy will cover up to $35,000 per claim / $100,000 aggregate for defense costs arising out of disciplinary, licensure, Medicare/Medicaid billing errors or similar administrative proceedings arising from covered incidents.*
Defense Attorney Provided
When needed, a defense attorney will be provided to represent you in court. Win or lose, legal fees in connection with a covered claim are covered without impacting your liability coverage limits.
Sexual Misconduct Defense
Your policy will cover up to $25,000 per policy period for amounts related to the defense of covered claims involving sexual misconduct.
HIPAA Defense Coverage
Information privacy coverage reimburses you up to $35,000 for costs related to claims alleging HIPAA violations, including relevant HIPAA fines.*
Loss of Earnings
Your policy will cover up to $2,500 per day / $35,000 aggregate for loss of earnings arising from a covered incident.
Biomedical Waste Hearing Expense
CM&F professional liability policies cover up to $10,000 for expenses arising out of biomedical waste hearings for covered incidents.
Personal Property of Others
Your policy will cover up to $1,000 aggregate for damages to personal property belonging to others, but for which you are responsible.
Additional Insured Endorsement at No Added Cost
With CM&F, there are no fees to add additional insureds to your policy. Additional Insured parties receive a shared limit with the First Named Insured for vicarious liability.
*For Maryland PAs, Administrative Hearing Expense Coverage and HIPAA Proceeding Expense Coverage carry an additional charge of $25.
*Please note that insurance can be complex, so please refer to your policy’s terms and conditions for more specific language related to your situation.
How Professional Liability Coverage Works For Physician Assistants
This section explains the steps by which a claim is handled under your CM&F Group professional liability (malpractice) policy.
| # | Step | Trigger | What Happens | Outcome |
|---|---|---|---|---|
| 1 | A Claim Is Filed | A patient alleges negligence, an error, or an omission in care. | A formal claim is initiated against you based on the alleged incident. | The claims process begins and must be reported to your insurer. |
| 2 | The Claim Is Reported to Your Insurer | You or a representative notify CM&F of the claim. | The claim is officially submitted under your professional liability policy and logged for handling. | CM&F reports the claim to MedPro, the underwriting carrier, which takes over handling from here. |
| 3 | A Claims Manager Is Assigned and Coverage Is Confirmed | The carrier takes over handling of the reported claim. | MedPro assigns a Claims Manager who gathers the relevant details of the incident and coordinates a coverage review with Coverage Counsel. | Coverage Counsel confirms whether the incident triggers coverage under your policy. If it does, the claim moves forward to legal defense. |
| 4 | A Defense Attorney Is Assigned | Coverage is confirmed and the claim moves into active defense. | MedPro assigns a qualified defense attorney and manages the legal process on your behalf. | You receive legal representation and guided defense strategy. |
| 5 | Legal Defense Costs Are Covered | Legal defense activities begin (e.g., attorney work, filings, court preparation). | Your policy covers defense-related legal expenses outside of your liability limits. | Your policy limits remain intact and are not reduced by defense costs. |
| 6 | You Retain Control Over Settlement Decisions | A settlement decision is proposed. | MedPro manages settlement, and no claim is settled without your explicit consent. | You maintain full control over whether a claim is settled or proceeds further. |
| 7 | A Settlement or Judgment Is Reached | The case resolves through settlement or court decision. | The policy pays covered damages up to the applicable limits, subject to policy terms. | Covered damages are paid up to your policy limits, protecting your personal assets from financial exposure. |
Additional Insurance Coverage Add-Ons
The following optional coverages bolt on to your CM&F Professional Liability policy for PAs, adding protection for exposures beyond your clinical practice, including coverage that can extend to other professionals you work with.
General Liability
General liability insurance for physician assistants provides coverage for non-professional risk exposures, including bodily injury or property damage that occur at the practice location and are not related to patient care.
Policies typically include limits such as $1 million per claim and $3 million aggregate, depending on the selected coverage.
Medical Director Coverage
Medical director coverage for physician assistants provides professional liability coverage for services performed in an administrative capacity on behalf of a third-party organization.
This coverage applies to non-clinical responsibilities such as oversight, protocol development, or supervisory functions, rather than direct patient care.
Supervising Physician Coverage
Supervising physician coverage allows a physician assistant policy to extend professional liability coverage to a designated supervising physician, where required.
This requires a separate application for approval. Coverage terms, eligibility, and cost vary based on the supervising relationship and underwriting requirements.
Ready to Secure Your Coverage?
Get an immediate quote on screen in as little as five minutes.
Apply with just a few clicks and download your proof of coverage instantly.
APPLYFrequently Asked Questions
The following questions address the most common concerns PAs have when evaluating physician assistant malpractice insurance, from policy structure and cost to claims handling and discounts. Each answer is designed to stand alone as a complete response.
You can reach us by phone, email, or chat, our team is here to help you find the right coverage for your practice.
What does physician assistant professional liability insurance cover?
Physician assistant professional liability insurance covers claims arising from patient care, including allegations of negligence, errors, or omissions. Coverage typically includes legal defense, settlements or judgments, and may extend to regulatory actions, license defense, and certain patient injury and/or property claims, depending on the policy terms.
Do physician assistants need their own malpractice insurance if covered by an employer?
Employer-provided malpractice insurance is designed to protect the healthcare organization, not the individual physician assistant. Individual professional liability insurance provides coverage that helps protect the PA’s personal assets and professional reputation if a claim is filed.
What is the difference between occurrence and claims-made coverage for physician assistants?
Occurrence coverage applies to incidents that happen during the policy period, regardless of when the claim is filed. Claims-made coverage applies only when both the incident and the claim occur while the policy is active, unless extended reporting coverage is in place. CM&F makes occurrence-based coverage the standard for PAs, so no tail coverage is required when a policy ends.
What is the difference between per occurrence and aggregate liability limits?
Your per occurrence limit, sometimes written as per claim, refers to the total amount the insurance company will pay per incident during the policy term. Your aggregate limit is the total amount the insurance company will pay for multiple claims over the course of one policy term, which is often one year.
What is the difference between per occurrence and aggregate liability limits?
Your per occurrence limit, sometimes written as per claim, refers to the total amount the insurance company will pay per incident during the policy term. Your aggregate limit is the total amount the insurance company will pay for multiple claims over the course of one policy term, which is often one year.
What factors affect the cost of malpractice insurance for physician assistants?
The cost of physician assistant malpractice insurance is based on your specialty risk tier, scope of practice, state and territory, selected coverage limits, and claims history. Higher-risk specialties and higher coverage limits typically result in higher premiums. Final premium is confirmed at application.
What are the P1, P2, and P3 specialty risk tiers for PAs?
[PLACEHOLDER]
Does my state's practice environment affect my malpractice coverage?
Physician assistants can be named individually in a malpractice claim or a licensing board complaint regardless of how their state classifies PA practice. Individual professional liability insurance helps protect a PA’s personal assets and license in any practice environment, because employer-provided coverage is designed to protect the organization rather than the individual provider. CM&F covers PAs in all 50 states across every practice category, and coverage travels with you if you move to a state with a different classification.
Does malpractice insurance cover telehealth services for physician assistants?
Malpractice insurance may include coverage for telehealth services when those services fall within the physician assistant’s licensed scope of practice and comply with applicable regulations and policy terms. All CM&F policies include telemedicine coverage at no additional charge.
Are there any discounts available for new graduates or those new to practice?
Yes. CM&F provides new-to-practice credits across most states and for the majority of our products. PAs receive an 80% credit in the first year post-graduation. The credit eases as you gain experience, decreasing in a staggered fashion to 60%, 40%, and 20%, before it levels out at the standard rate.
Are there any risk management programs available that could lower my premiums?
Yes. PAs who are members of the AAPA can complete a selection of risk management courses through CM&F. Completing a course leads to a 10% discount on your premium, valid for three years, so a course completed this year carries the discount this year and the next two. Taking another course every three years maintains the discount, and the courses also count toward Continuing Education credits.
How does a malpractice claim work for a physician assistant?
A malpractice claim begins when a patient alleges negligence, an error, or an omission in care. Once a claim is reported, the professional liability insurance policy provides access to legal defense and manages the claims process on behalf of the physician assistant. The insurer investigates the claim, appoints defense counsel, and covers legal costs, settlements, or judgments, subject to the policy’s terms and coverage limits.
How do I transfer my existing liability policy to CM&F without a gap in coverage?
If you have an occurrence policy, you can purchase your CM&F professional liability policy when your current policy expires. The online application lets you select a coverage date up to 30 days in advance, so you do not have to return and apply on the exact day. If your current policy is claims-made, it is best to discuss transition options with a CM&F service professional, who will help ensure there are no gaps in your coverage.
What is Asset Guard supplemental liability insurance for physician assistants?
Asset Guard is supplemental coverage designed for physician assistants employed as W-2 staff in hospitals, physician groups, or practices. Unlike policies for independent contractors or practice owners, it protects PAs only for services provided within their scope of employment. It offers occurrence-based protection at $100,000 per claim and $300,000 aggregate, helping employed PAs safeguard their careers where an employer policy is not enough.
What is PA moonlighting malpractice insurance?
Moonlighting is when physician assistants take on extra shifts or side jobs outside their main employer. Employer malpractice policies usually do not cover this additional work, leaving PAs personally exposed to liability. PA moonlighting malpractice insurance provides a separate, discounted class for side work, covering per diem, locum tenens, or part-time roles, so PAs stay safeguarded against claims that fall outside their primary employment.
CM&F Trusted Provider to
CM&F has stood behind healthcare professionals through every shift in the market, the regulatory environment, and the practice of medicine itself. That commitment doesn't waver and neither does your coverage.

Coverage That Travels With You
Your policy moves with you across employers, practice settings, and state lines, always protecting your personal assets and license.
A Century of Commitment
In business since 1919, CM&F’s long-standing experience in the insurance market means deeper expertise.
No Surprises at Separation
Occurrence-based coverage means no tail coverage costs when you retire or change jobs - permanent protection built in.
Your Defense. Your Decision.
Full consent to settle means you control your defense from start to finish. CM&F will never settle a claim without your approval.
Have Questions?
Have questions about CM&F professional liability insurance policies? Call or email using the details below, or click the Chat icon in the bottom right corner of your screen. For more commonly asked questions, refer to our FAQ page.


CM&F Means Peace of Mind
CM&F Group was founded over a century ago. Through up and down markets, CM&F’s dedication to healthcare professionals has never wavered.
CM&F remains committed to making it easy and cost-effective to secure vital professional insurance coverage.
- Future-Proof Care
- Time-Tested Trust
- We Keep It Simple
- We’re Your Ally