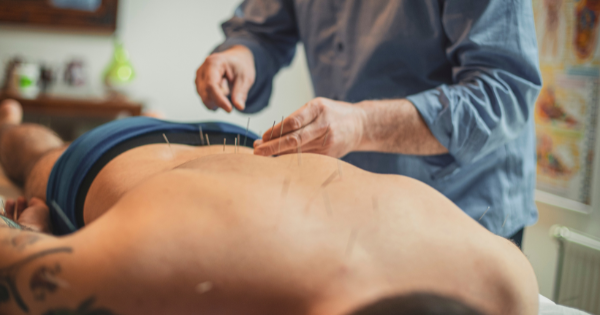
After a busy day of appointments, you get a call that happens to the most seasoned acupuncture providers. A patient discovered a needle inadvertently left in place following treatment. Despite diligently tracking the number of needles you use at every appointment, you still forget a needle once in a while.
Most patients remove the needle and move on. Some, though, contact you with concerns.
Now, you have questions of your own. Did you document the treatment appropriately? What should you do next? What happens if the patient files a malpractice claim?
Malpractice claims in acupuncture are rare, but a clinical incident can, nonetheless, spiral into a business concern.
Protecting your acupuncture practice means looking at the entire business, from the care you provide and the systems you use to the space where you work and the people you hire.
When Clinical Incidents Become Business Risks for Acupuncture Practices
A retained needle is one example of a safety incident, but other incidents can happen in any acupuncture practice.
In a review of acupuncture-related patient safety reports from England’s National Health Service, where acupuncture is common and covered by insurance, retained needles are among the most common incidents reported. Other complaints include dizziness, loss of consciousness/unresponsive, falls, bruising or soreness at the needle site and other adverse reactions. Most (95%) incidents were categorized as low or no harm.
Any incident, even if it doesn’t result in serious harm, requires acupuncturists to respond appropriately, document what happened and address a patient’s concerns.
Professional liability, often called malpractice insurance, covers claims alleging that a practitioner’s professional services caused harm. CM&F’s current professional liability coverage for acupuncturists includes up to $1 million per claim and up to a $6 million aggregate, depending on the policy selected and its terms.
If you’re a solo acupuncturist, that coverage helps protect you as the individual practitioner. Owning a business creates risks that extend beyond the treatment itself and requires more coverage.
How to Build Risk Management Into Your Acupuncture Practice Operations
Insurance can help protect your practice when a covered claim occurs. Risk management helps reduce the likelihood of incidents in the first place.
For acupuncture practices, risk management means making safety part of your workflow rather than something you think about only after a problem.
Practice owners should also consider whether their procedures consistently address needle safety, infection control, sharps handling and disposal, documentation, informed consent and incident response.
The Council of Colleges of Acupuncture and Herbal Medicine’s Clean Needle Technique Manual provides national guidance on acupuncture needle safety, bloodborne pathogens, office procedures and risk reduction. Every provider needs to find what works for them, such as using a counting device or a laminated drawing of the body to count needles.
The Occupational Safety and Health Administration says contaminated sharps must be disposed of immediately or as soon as feasible in appropriate sharps containers, and its Bloodborne Pathogens Standard establishes additional requirements for covered employers. State and local rules may impose additional requirements.
Policies are only as effective as the extent to which they are known and implemented. Procedures need to work during a full schedule, when rooms are turning over and competing demands pull your attention in different directions.
Strong systems make safety routine.
Insurance Coverage Every Acupuncture Practice Owner Should Consider
When the acupuncture practice belongs to you, your insurance coverage must protect your ability to practice acupuncture, plus the business and any employees you hire.
General Liability Insurance for Your Acupuncture Clinic
Not every patient injury is related to acupuncture. If you own a brick-and-mortar clinic, a patient could slip on a wet floor or icy sidewalk. A patient or a passerby could damage the property. Both are scenarios that require general liability insurance.
Professional liability: Generally addresses covered claims related to your professional services.
General liability: Addresses certain bodily injury and property damage risks that arise from operating a business.
CM&F offers general liability as an add-on for self-employed acupuncturists and acupuncture group policyholders.
How to Protect Patient Data at Your Acupuncture Practice
Acupuncture practices are considered a “covered entity” under HIPAA and must follow patient privacy laws. Unless you operate a cash-only business and never communicate about a patient electronically, you must stay compliant with HIPAA laws. This means keeping intake forms, health histories, contact information, appointment schedules, billing records and clinical documentation all private.
Cyber liability coverage addresses costs and liabilities associated with events such as data breaches and cyberattacks. Of course, insurance should complement, not replace, good data-security practices. Review any vendors who can access patient information, how accounts and devices are secured and how data is stored and backed up.
Employee Insurance Coverage for Acupuncture Practice Owners
Hiring your first practitioner is a milestone that changes your business’s risk profile. CM&F offers group liability coverage for acupuncture clinics and teams of licensed acupuncturists.
Some other insurance carriers require you to list every employee you hire, so be sure you’re familiar with your provider’s protocol.
Most states require you to have a workers’ compensation policy once you hire your first employee. An acupuncturist who gets injured on the job is a workers’ comp claim, not a malpractice claim.
Insurance Considerations When Adding Services to Your Acupuncture Practice
Depending on your patient needs and practice growth, you may decide to incorporate other modalities and services alongside acupuncture care. What a licensed acupuncturist is permitted to provide varies by state, so be sure you’re practicing within your scope.
Before adding a service, don’t assume that because it’s common within the profession, your existing license, training or insurance automatically covers it.
Confirm the state rules where you practice and review your policy terms. When you’re uncertain, ask your licensing board, legal counsel or insurance provider before offering the service.
Finally, as your acupuncture practice grows, each change is an opportunity to ask whether your risk has changed since you last reviewed your insurance and operating procedures. If so, your protection may need to change with it.
CM&F protects acupuncture clinicians with professional liability coverage, helping keep your practice protected as you grow. Learn how CM&F can help protect your acupuncture practice and get a quote in minutes using the chatbox on our website.